CRM and GDPR in Malta: How to Keep Customer Data Compliant
How to run a GDPR-compliant CRM in Malta: lawful basis, marketing consent, EU hosting, access roles, retention, data requests and breaches, in plain steps.
Systems & AI · Insurance
Malta Digital builds CRM in Malta for businesses that live on renewals, and insurance brokers and agents depend on them more than most. One client can hold a car, a home and a health policy, each with its own date and insurer. This guide shows what a broker CRM should hold, the rules it can keep for you, a worked example and a free planner.
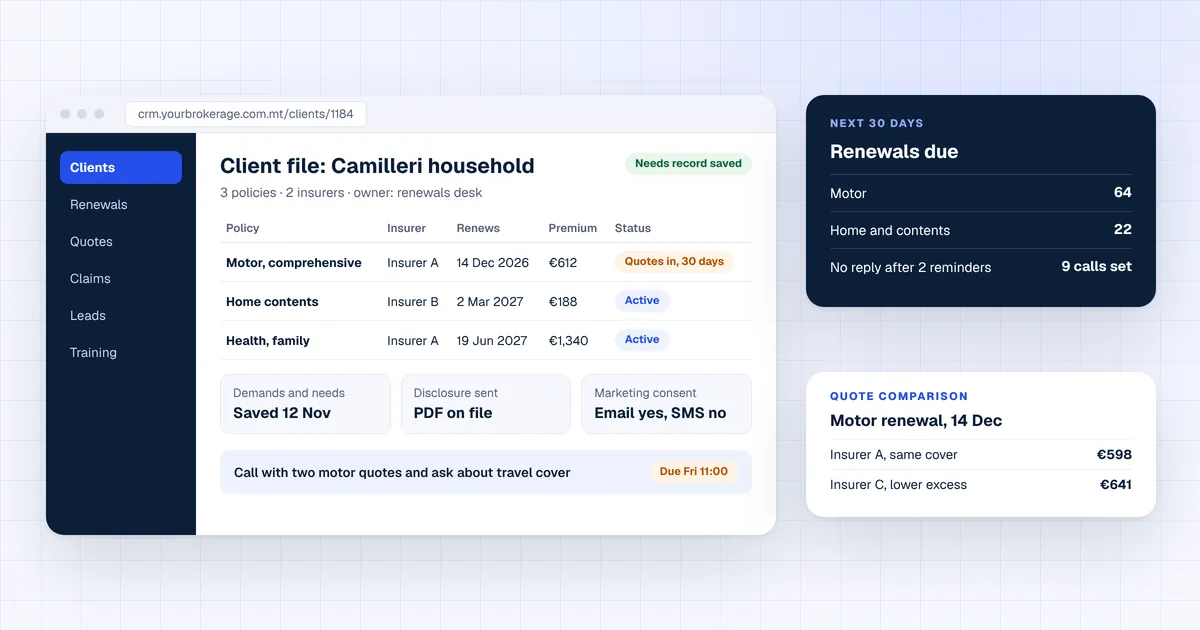
A CRM for an insurance broker keeps every client, policy, renewal date, quote and claim on one file. It reminds you before each renewal, stores the demands and needs record for every sale and shows which clients hold only one policy. Malta had 468,367 licensed vehicles at the end of September 2026 (NSO), and each one needs third-party cover. Malta Digital builds broker CRMs that connect to the insurer portals and tools you already use, from €7,500.
The short version
Most broker offices run on an insurer portal, a spreadsheet of renewals and a busy inbox. It works until a renewal slips, or a client calls and nobody can see what was said last year.
Every policy, household member, document and call in one place.
Reminders 60, 30 and 14 days before each policy ends.
The needs record for each sale, saved with the policy it led to.
Quotes from each insurer stored with the reason for the choice.
Claim number, status, contacts and next step on the client file.
Web forms and ad leads land with a person and a reply deadline.
It does not replace the insurers’ portals. It sits above them, so your team has one view of the client while each insurer keeps its own system.
Malta data
At the end of September 2026, Malta had 468,367 licensed motor vehicles, NSO figures show. The stock grew by 4,633 in three months, about 50 vehicles a day. Under Cap. 104, nobody may use a motor vehicle on a road without third-party cover in force.

Every one of those vehicles is a policy with a renewal date. Add homes, health, travel and business cover, and a small broker can be tracking thousands of dates. That is a job for a system, not a memory.
The rules
Insurance distribution in Malta follows the EU Insurance Distribution Directive, put into Maltese law through Cap. 487. Several of its rules are really record-keeping rules. A CRM either keeps them on the file or leaves them to memory.
| Rule | What it says | What the CRM does |
|---|---|---|
| IDD Article 17(1) | Act honestly, fairly and professionally, in the best interests of the client | Keeps the reason for each recommendation next to the quote that was chosen |
| IDD Article 20(1) | Specify the client’s demands and needs before the contract, and propose only contracts that fit them | Makes the needs record a required step before a quote can be sent |
| IDD Article 19 | Tell the client, in good time, if your advice is based on a fair analysis or tied to certain insurers, and how you are paid | Sends the disclosure with the first offer and saves the date it went out |
| IDD Article 23 | Give this information on paper or another durable medium (such as a PDF sent by email), clearly and free of charge | Saves each document sent as a PDF on the client file |
| IDD Article 10(2) and Cap. 487 article 14A | At least 15 hours of professional training or development a year | Tracks training hours per person against the yearly target |
| S.L. 586.01, regulation 9 | Marketing emails and texts need prior consent, with a narrow exception for existing customers | Keeps a consent flag per channel and an opt-out in every message |
Demands and needs come first. Under Article 20 of the IDD, before an insurance contract is made you must specify the client’s demands and needs from what they tell you, and any contract you propose must fit them. A CRM can make that record a required step before a quote is sent.
Apply now and tell us how many policies you look after, which insurers you work with and how you track renewals today. We reply with what we would build first.
Free tool
Put in your policies, commission, renewal rate and single-policy clients. The planner works out the extra commission on-time renewals and one more policy per client could bring, and the admin time a CRM could free. Nothing you type leaves this page.
Starting numbers match the worked example below. Replace them with yours.
Your result appears here as you type.
The renewal journey
Here is the path every renewal can take in a good system. Each step adds to the same client file, so anyone in the office can pick it up.
Grow the book
Most broker growth comes from clients you already have. A CRM shows who holds only one policy and when it is a fair moment to ask about another.
The renewal call is a natural time to ask about home cover.
A new address on the file can prompt a home contents review.
A new driver or child changes needs on motor, health and travel.
Clients who run a firm may need liability or business cover.
Worked example
Here is an example broker, not a client: 2,500 policies, average commission of €70 a policy a year, and 82% of policies renewed. These are the planner’s starting numbers, so you can change them to your own.
| Item | Today | With a broker CRM | Difference |
|---|---|---|---|
| Policies renewed | 82% of 2,500, so 450 lost a year | 4 more points kept with on-time reminders and calls | about 100 policies, €7,000 a year |
| Second policies | 1,200 clients hold only one policy | 5% add one when asked at renewal | about 60 policies, €4,200 a year |
| Renewal admin | 20 minutes each, about 208 renewals a month | Half the steps handled by the CRM | about 35 hours a month |
| Payback on a €7,500 CRM | No system | About €11,200 a year in extra commission | about 8 months, before time saved |
The two biggest numbers come from renewals that slip and clients nobody asked about a second policy. Neither needs more advertising, only a system that remembers.
Your options
Each insurer’s portal for its own policies, plus a renewal list kept by hand.
Best for: Small agencies tied to one insurer.
Good at contacts and email. Policies, renewals and the needs record must be added and kept in sync.
Best for: Brokers with few policy types and simple renewals.
Built around your policy types, insurers and rules, connected to the tools you keep. You own the code.
Best for: Brokers with several insurers, many renewal dates and records to keep.
Read how to keep client data safe in our guide to CRM and GDPR, and how fast replies win leads in lead follow-up automation.
Proof
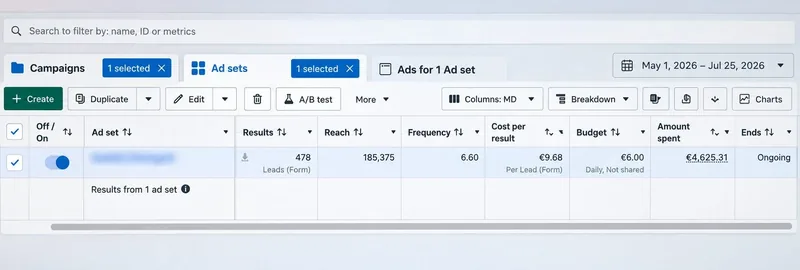
For one client, a lead form campaign on Facebook and Instagram brought 478 form leads from 1 May to 25 July 2026, at €9.68 per lead. Leads like these turn into policies only when each one gets a fast reply and a clear next step. That is what a broker CRM adds: an owner, a reply deadline and a follow-up plan on every lead, then a renewal date once they buy.
A few straight answers
A system that keeps every client, policy, renewal date, quote, claim and needs record on one file, with reminders before each renewal and a clear owner for every lead.
No. Each insurer keeps its own system. The CRM sits above them, so your office has one view of the client and every renewal.
Article 20 says that before a contract is made you must specify the client’s demands and needs from what they tell you, and any contract you propose must fit them.
The IDD sets at least 15 hours of professional training or development a year. In Malta, Cap. 487 article 14A applies this through the MFSA’s rules.
Only clients who agreed, or existing customers under the narrow exception in S.L. 586.01 regulation 9, with an opt-out in every message.
We suggest about 60 days before the end date, so there is time to get terms, refresh the needs check and call clients who do not reply.
Malta Digital builds custom CRM systems from €7,500. The price depends on your policy types, users and the tools it connects to, with a written quote first.
NSO Malta: Motor Vehicles: Q3/2026 (NR 207/2026) · Laws of Malta: Cap. 104, Motor Vehicles Insurance (Third-Party Risks) Ordinance, article 3 · Directive (EU) 2016/97 on insurance distribution (IDD), articles 10, 17, 19, 20 and 23 · Laws of Malta: Cap. 487, Insurance Distribution Act, article 14A · GDPR, Regulation (EU) 2016/679 (EUR-Lex) · Laws of Malta: S.L. 586.01, Processing of Personal Data (Electronic Communications Sector) Regulations, regulation 9 · IDPC Malta: Direct marketing
Keep reading
How to run a GDPR-compliant CRM in Malta: lawful basis, marketing consent, EU hosting, access roles, retention, data requests and breaches, in plain steps.
How to automate lead follow-up in Malta: instant WhatsApp and email replies, one lead list, a follow-up schedule, where AI helps and what to keep human.
How Meta and Facebook lead ads work: instant forms on Facebook and Instagram, setup, testing, where leads go and how Malta businesses reply fast enough to win.
A useful first step
Tell us how many policies you look after, which insurers you work with and how you track renewals today. We reply with what we would build first and what a CRM that fits would cost.
Step 1 of 3
A few quick questions, about a minute. We usually reply within 2–3 hours.